C.K. Gupta
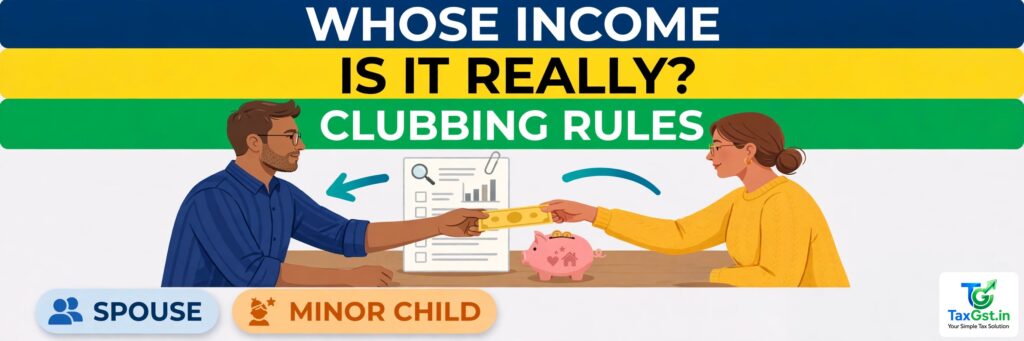
If you transfer an asset to your spouse without adequate consideration, the income from that asset is still taxed in your hands — that is clubbing. The same applies to income of a minor child (clubbed with the higher-earning parent, with a ₹1,500 exemption per child per year) and to assets transferred to your son’s wife. Genuine gifts that are not routed back to you, and income the recipient earns from their own skill, are not clubbed. Verified November 2026 · TaxGST.in
A reader wrote in with a familiar plan: put ₹10 lakh in his wife’s name as a fixed deposit, earn interest at her lower slab, and save tax. It sounds tidy. It does not work — and the reason has a name: clubbing. The tax department taxes income in the hands of the person who really owns the money, not the name on the account.
Clubbing is one of those rules that catches honest people, because the arrangement feels like a gift, not a dodge. This guide explains exactly when income gets pulled back into your return, when it doesn’t, and the legitimate ways couples actually save tax — starting with the deductions hub’s complete tax-saving guides — and if you are also wondering about gifts themselves, read the gift-tax guide: the ₹50,000 rule and the fully-exempt relative list alongside this one.
The core rule: transfer without consideration
The clubbing provisions (carried into the Income-tax Act, 2025 from Sections 60–64 of the Income-tax Act, 1961) say this: if you transfer an asset, directly or indirectly, to your spouse otherwise than for adequate consideration, the income from that asset is deemed to be yours. Your wife’s fixed deposit funded by your money? The interest is taxed in your return, at your slab. A house bought in her name with your funds and then rented out? The rent is yours for tax purposes.
Two words do the heavy lifting. “Adequate consideration” means she paid fair value — her own money, a genuine loan she repays, assets of equivalent value exchanged. And “directly or indirectly” closes the obvious workaround: routing the money through a relative or a trust does not break the chain if the substance is the same transfer.
The three clubbing cases that matter
1. Spouse
Income from assets transferred to a spouse without adequate consideration is clubbed with the transferor. But note the limits: if your spouse then invests that income further, the second-generation income is hers. Example: you gift your wife ₹5 lakh; she puts it in a deposit earning ₹35,000 interest — that ₹35,000 is taxed in your hands. If she then invests the ₹35,000 interest itself and earns ₹2,500 on it, that ₹2,500 is her income. The clubbing applies to the income from the transferred asset, not to income from the income.
There is also a specific carve-out people miss: income your spouse earns from her own skill, knowledge or professional qualification is never clubbed, even if you funded the setup. A spouse who is a doctor, designer or consultant keeps her professional income as her own.
2. Minor child
Income of a minor child is clubbed with the parent whose total income (excluding the child’s income) is higher. The one relief: an exemption of ₹1,500 per minor child per year is available to that parent. Example: your 12-year-old earns ₹20,000 interest on a deposit you funded. ₹1,500 is exempt; the remaining ₹18,500 is added to the higher-earning parent’s income.
The exception: a minor child’s income from their own manual work, skill, talent or specialised knowledge is not clubbed — a child actor’s or young athlete’s earnings stay theirs. Income from a minor child with a disability (as specified in the law) is also excluded from clubbing.
3. Son’s wife (daughter-in-law)
Assets transferred to your son’s wife without adequate consideration follow the same rule: the income is clubbed with yours. This is the provision families most often trip over when “helping” a newly married couple with an investment in the daughter-in-law’s name.
What is NOT clubbed — the legitimate routes
- Genuine gifts from relatives that stay gifts. A gift received from a specified relative is exempt in the recipient’s hands (see the gift guide linked above) — but if you gift an asset to your spouse, the income still clubs back to you. The exemption is about the gift itself, not the income it later produces in a spouse’s hands.
- Income from the recipient’s own efforts. Salary, professional fees and business profits earned by the spouse or child themselves are their own.
- Assets bought with the recipient’s own money. If your wife invests her own salary, savings or inheritance, the income is hers — keep the money trail clean to prove it.
- Second-generation income. As shown above, income earned on already-clubbed income belongs to the recipient.
- HUF partition and genuine family settlements have their own treatment — take advice rather than assuming clubbing does or doesn’t apply.
So how do couples legitimately save tax? The honest routes are unglamorous: both spouses genuinely earning and investing their own incomes; using each spouse’s own deductions fully (for example, health premiums and the deductions covered in the deductions hub’s saving guides); and, where a spouse has genuinely lower income, routing new savings from that spouse’s own income into their investments. What does not work is relabelling your income as hers.
A worked example
Rahul, in the 30% slab, transfers ₹10 lakh to his wife Priya, who invests it at 7% — ₹70,000 annual interest. Clubbed: the ₹70,000 is added to Rahul’s income and taxed at 30% (₹21,000), not at Priya’s lower slab. If instead Priya invests ₹10 lakh of her own salary savings at the same rate, the ₹70,000 is hers, taxed at her slab — potentially nil if her total income stays within the basic exemption. Same investment, same return, entirely different tax outcome — and the only difference is whose money it genuinely was. Keep bank statements that prove the source; in a scrutiny case, the paper trail is the argument, as the scrutiny-notice guide explains.
FAQs
Can I avoid clubbing by gifting money to my wife and letting her invest it?
No — income from assets transferred to a spouse without adequate consideration is clubbed with the transferor, even if the gift itself is exempt.
Is my minor child’s bank interest taxed in my hands?
Yes, with the higher-earning parent, after a ₹1,500 exemption per child per year — except income from the child’s own skill or work, and specified disability cases.
What counts as adequate consideration?
Fair value paid by the recipient — their own funds, or a genuine loan or exchange of equivalent assets. A paper loan that is never repaid will not survive scrutiny.
Does clubbing apply to a gift from my parents to me?
No — gifts from specified relatives are exempt in your hands, and the income from an asset your parents gifted you is yours. Clubbing bites on transfers to your spouse, minor child or son’s wife.
What if both parents earn — whose return takes the child’s income?
The parent with the higher total income (excluding the child’s income) in that year.
Sources
Clubbing of income provisions of the Income-tax Act, 2025, carried forward from Sections 60–64 of the Income-tax Act, 1961 — transfer to spouse without adequate consideration, income of minor child (₹1,500 exemption per child), transfer to son’s wife, and exclusions for income from the recipient’s own skill or specialised knowledge. Gift-tax framework (₹50,000 threshold for non-relatives; specified relatives fully exempt) per the gift provisions of the Income-tax Act, 2025, as covered in TaxGST.in’s gift-tax guide. All figures verified against the statutory scheme as in force for Tax Year 2026-27.
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.