C.K. Gupta
From tax year 2026-27, HRA exemption is 50% of salary in eight metro cities and 40% elsewhere, Form 124 replaces Form 12BB for HRA claims, and landlord PAN is mandatory when annual rent crosses ₹1 lakh. The exemption still follows the old formula — least of actual HRA, rent minus 10% of salary, and the metro or non-metro percentage — but the paperwork and the city list have changed. Verified November 2026 · TaxGST.in
Rohan pays ₹18,000 a month in rent in Delhi and receives ₹25,000 a month as HRA. For years his employer exempted the full HRA from TDS. From April 2026, the calculation is the same but the form and the proof change — and if he files the old form, his employer may stop exempting anything at all.
The 8 metros at 50%
From 1 April 2026, the cities that qualify for the 50% rate are Delhi, Mumbai, Kolkata, Chennai, Bengaluru, Hyderabad, Pune and Ahmedabad. That is eight metros, up from four. Everywhere else, the rate is 40%.
The city that matters is where you actually live and pay rent, not where your employer is registered. If you move mid-year, the exemption is worked out for each period separately.
How the exemption is calculated
The exemption is the least of: actual HRA received, rent paid minus 10% of salary, and 50% of salary in a metro or 40% elsewhere. Salary means basic plus dearness allowance plus commission on a fixed percentage of turnover.
A worked example
Rohan’s numbers: salary ₹60,000 a month (₹7,20,000 a year), HRA ₹25,000 a month (₹3,00,000 a year), rent ₹18,000 a month (₹2,16,000 a year), living in Delhi — a metro.
- Actual HRA: ₹3,00,000.
- Rent minus 10% of salary: ₹2,16,000 − ₹72,000 = ₹1,44,000.
- 50% of salary: ₹3,60,000.
The least is ₹1,44,000 — so Rohan’s exempt HRA is ₹1,44,000, not the full ₹3,00,000 he receives. The remaining ₹1,56,000 is taxable salary.
Now suppose Rohan’s rent rises to ₹25,000 a month (₹3,00,000 a year). Then rent minus 10% of salary is ₹3,00,000 − ₹72,000 = ₹2,28,000, which becomes the least figure. The exemption rises, but it is still capped by the formula — it never equals the full HRA unless the rent is high enough.
Form 124 replaces Form 12BB
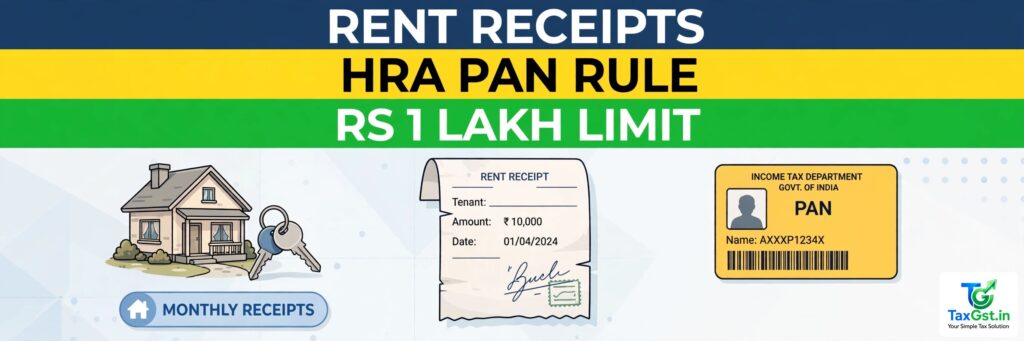
Form 12BB was the declaration employees gave their employer for TDS. For HRA claims from 2026-27, Form 124 replaces it. The new form asks for the landlord’s name and PAN (where required), the monthly rent, the period of tenancy, and the address of the rented accommodation, in a structured format the employer can verify.
File Form 124 before your employer finalises TDS for the year. If you file the old form, the employer may treat the claim as unsupported and deduct TDS on the full HRA.
The ₹1 lakh PAN rule
Landlord PAN is mandatory when the annual rent crosses ₹1 lakh — that is, more than ₹8,333 a month on average. Below that, a landlord declaration is enough. The rule is per landlord: if you pay two landlords, each is assessed separately.
A wrong PAN is worse than a missing one. It can lead to the claim being disallowed and the landlord receiving a notice for income they did not declare.
Claim-killers
- Paying rent to a spouse or parent without a genuine tenancy and without the landlord declaring the income.
- Claiming HRA for a house you own, or for a period you did not live there.
- Cash rent with no agreement and no receipts.
- Rent receipts that do not match the bank transfers.
No HRA, no section 80GG either. If you live in your own house and pay no rent, you cannot claim HRA. And section 80GG — the fallback for people without HRA — is only for those who do not own a house in the place of employment and do not receive HRA. It does not rescue an HRA claim that was never valid.
What to do before the next TDS cycle
- Confirm your city is on the 8-metro list and which rate applies.
- File Form 124, not Form 12BB, for HRA.
- Get your landlord’s PAN if annual rent crosses ₹1 lakh.
- Keep the rent agreement, receipts and bank statements for the full year.
- Run the three-figure formula yourself before accepting your employer’s calculation.
FAQs
Do I need Form 124 if my employer already deducted TDS?
You can still claim the exemption in your return, but the TDS already deducted is only recovered through the return.
Can I claim HRA and a home-loan deduction together?
Only for different properties — for example, HRA for a rented house in the city of work and a home loan for a house elsewhere. Not for the same house.
What if my landlord refuses to give PAN?
You cannot claim the exemption above the ₹1 lakh threshold without it. A declaration does not substitute for PAN above that limit.
Sources
Section 10(13A), Income-tax Act, 2025; Rule 2A and Form 124; CBDT notification on the 8-metro list dated 1 April 2026; Finance Act, 2026 (HRA provisions).
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.