C.K. Gupta
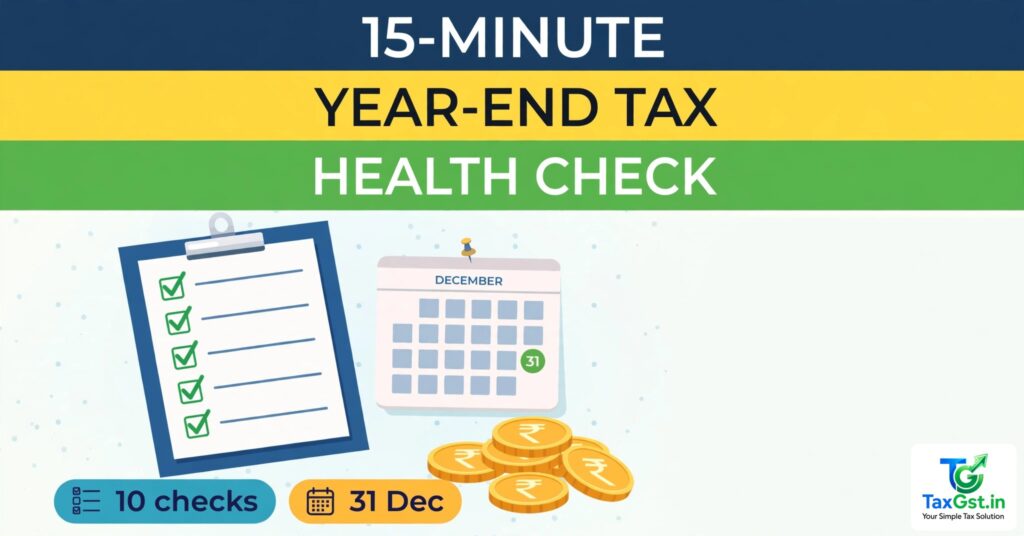
Ten checks, fifteen minutes: confirm your regime choice, top up Section 80C to ₹1.5 lakh and NPS by ₹50,000 under 80CCD(1B), pay health premiums before 31 March, pay the third advance-tax instalment (75% cumulative) by 15 December 2026, gather HRA proof with your landlord’s PAN if rent exceeds ₹1 lakh a year, harvest capital losses before 31 March, match your AIS against Form 26AS, and remember the 31 December 2026 deadlines — belated ITR for AY 2026-27 and the FAST-DS window both close that day. Verified November 2026 · TaxGST.in
It is 8 November. The financial year ends on 31 March — just under five months away — and nearly every tax-saving move available to a salaried person has a deadline attached to it. The moves are small: a top-up here, a document there, one instalment paid on time. The cost of missing them is not: a ₹46,800 deduction lost here, 1% a month in interest there, a refund that never arrives. Run this 10-point self-audit in fifteen minutes with your payslip, bank app and AIS open.
For the full deductions picture, start with the deductions hub — 80C, 80D, NPS and every saving route in one place.
1. Regime check — the decision everything else hangs on
Are you in the old regime or the new regime? If you never opted out, you are in the new regime — and Sections 80C, 80D, HRA and LTA give you nothing at all. The old regime only pays if your deductions beat the new regime’s lower slabs and its ₹75,000 standard deduction. The quick test: add up 80C (up to ₹1.5 lakh), 80D, HRA exemption and home-loan interest. Below roughly ₹2.5–3 lakh, the new regime usually wins; above it, run the numbers properly. The guide to deductions beyond 80C lists every section in the stack.
2. Section 80C — fill the ₹1.5 lakh bucket
Check what you have already put in this year: EPF, PPF, ELSS, life-insurance premium, children’s tuition fees, home-loan principal. If the total is short of ₹1.5 lakh and you are in the old regime, a top-up before 31 March 2027 is the highest-return move on this list — at the 30% slab, the full ₹1.5 lakh saves ₹46,800 including cess. ELSS has a 3-year lock-in and market risk; PPF is a 15-year commitment; a term-plan premium is often the simplest filler.
3. NPS — the extra ₹50,000 most people forget
On top of 80C, Section 80CCD(1B) gives an additional ₹50,000 deduction for your own NPS contribution — old regime only. At the 30% slab that is another ₹15,600 saved. A ₹50,000 contribution made in March still counts for the full year — until you forget it entirely, which is what usually happens. Work out your numbers on the NPS calculator first. The employer’s NPS contribution under Section 80CCD(2) is separate and works in the new regime too, up to 14% of salary.
4. Health insurance — pay the premium before 31 March
Section 80D allows up to ₹25,000 a year for health cover for yourself, spouse and children, plus a separate ₹25,000 for parents — rising to ₹50,000 per head where the insured are senior citizens, so up to ₹1,00,000 in total. Premiums must be paid by a non-cash mode, and a ₹5,000 slot for preventive health check-ups sits inside the same limit. Two things to check now: is your premium actually paid for this year, and are your parents covered — their ₹50,000 senior limit is the biggest unused 80D head in most families. The Section 80D guide has the limits table and the regime warning: 80D exists only in the old regime.
5. Advance tax — the 15 December instalment
If your tax payable after TDS exceeds ₹10,000, advance tax applies, and the third instalment falls on 15 December 2026 — by which date 75% of your total liability for the year must be paid. Miss it and interest under Section 234C runs at 1% per month on the shortfall. Salary-only taxpayers are usually covered by employer TDS, but anyone with FD interest, capital gains, rent or freelance income is exposed. Check the amount on the advance tax calculator, and fold any bonus, property sale or gains booked this year into the 15 December payment. The advance-tax guide explains the 234B/234C interest maths with worked instalments.
6. HRA — receipts and the landlord’s PAN
If you claim HRA, two documents decide whether the claim survives: rent receipts for the year and your landlord’s PAN if annual rent exceeds ₹1 lakh. No PAN above ₹1 lakh, no exemption — the claim fails on paperwork, not on merit. Get the receipts now, while the landlord remembers the year. If your employer needs a declaration, the form for tax year 2026-27 is Form 124 — the HRA rules guide covers the 8-metro change and the Form 124 process.
7. Harvest capital losses before 31 March
Losses from shares and mutual funds can be set off against gains — short-term losses against both short- and long-term gains, long-term losses only against long-term gains — and unadjusted losses can be carried forward for 8 years, but only if you file on time. Equity long-term gains up to ₹1.25 lakh a year are exempt, so there is no point harvesting gains below that line; selling a loss-making position you no longer believe in before 31 March banks a loss against this year’s gains.
8. Match your AIS against Form 26AS
Open your Annual Information Statement and Form 26AS (Form 168 from tax year 2026-27) and check three things: every TDS entry matches what was actually deducted, no income appears that is not yours, and no income you earned is missing. A mismatch found in November is a five-minute correction; after filing, it is a notice. If TDS was deducted but is missing, the fix is in the guide to TDS missing from 26AS/AIS.
9. The 31 December 2026 deadlines — two windows close
Two windows shut on 31 December 2026. First, the belated return for AY 2026-27: if you missed the July or August deadlines, a belated return under Section 139(4) is still possible till 31 December — with late fee up to ₹5,000 under Section 234F and no carry-forward of business losses. Second, FAST-DS: the foreign-assets disclosure window (16 August to 31 December 2026) closes the same day — undisclosed foreign assets up to ₹1 crore can be regularised at 30% tax plus an equal penalty, and taxed-but-unreported assets up to ₹5 crore for a flat ₹1 lakh fee.
10. The five-minute document file
Make one folder — physical or digital — with this year’s rent receipts and landlord PAN, health-premium receipts, NPS and PPF statements, capital-gains statements and your AIS/26AS downloads. Every one is something an assessing officer can ask for, and ten times harder to find in July than in November.
Your 10-point scorecard
| # | Check | Deadline | At stake |
|---|---|---|---|
| 1 | Regime: old vs new | Before investing | Up to ₹46,800+ |
| 2 | 80C filled to ₹1.5 lakh | 31 Mar 2027 | Up to ₹46,800 |
| 3 | NPS extra ₹50,000 (80CCD(1B)) | 31 Mar 2027 | Up to ₹15,600 |
| 4 | 80D health premium paid | 31 Mar 2027 | Up to ₹31,200 |
| 5 | Advance tax — 75% by 15 Dec | 15 Dec 2026 | 1%/month interest |
| 6 | HRA receipts + landlord PAN | Before March | Full exemption |
| 7 | Harvest capital losses | 31 Mar 2027 | Tax on gains set off |
| 8 | AIS vs Form 26AS matched | Now | Notices avoided |
| 9 | Belated ITR / FAST-DS | 31 Dec 2026 | Windows close |
| 10 | Document file created | Now | Scrutiny-ready |
FAQs
Is it too early in November to do a year-end tax check?
No — that is the point. The December deadlines (advance tax on 15 December, belated ITR and FAST-DS on 31 December) are weeks away, and the March moves (80C, NPS, 80D) are cheapest spread over the remaining months rather than crammed into the last week.
Can I still file ITR for AY 2026-27 if I missed the deadline?
Yes — a belated return under Section 139(4) till 31 December 2026, with late fee up to ₹5,000. A revised return stays open till 31 March 2027.
Sources
Sections 80C (Section 123, Income-tax Act, 2025), 80D (Section 126), 80CCD(1B) and 80CCD(2) — limits and regime availability. Sections 234B and 234C — advance-tax interest; third instalment 15 December 2026 (75% cumulative). Section 139(4) — belated return till 31 December 2026; Section 139(5) — revised return till 31 March 2027; Section 234F — late fee up to ₹5,000. Section 112A — equity LTCG exemption ₹1.25 lakh a year. CBDT Circular No. 07/2026, dated 28 September 2026. FAST-DS: CBDT notification, Form 1 window 16 August – 31 December 2026. HRA: landlord PAN above ₹1 lakh annual rent; Form 124 for tax year 2026-27.
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.