C.K. Gupta
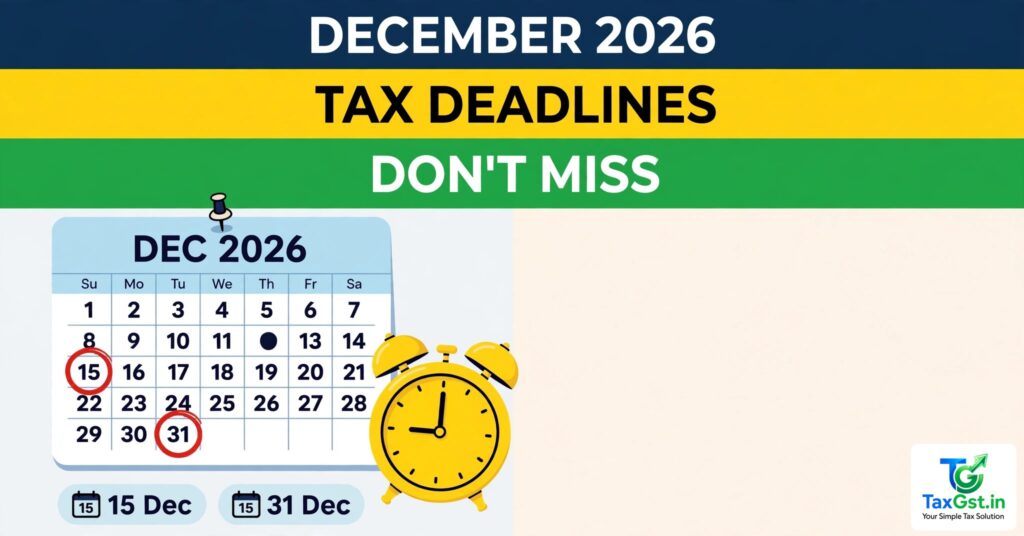
December 2026 closes four separate tax clocks: the third advance-tax instalment (75% cumulative) on 15 December, the GSTR-9 and GSTR-9C annual returns for FY 2025-26 on 31 December, belated income-tax returns for AY 2026-27 on 31 December, and the FAST-DS foreign-assets disclosure window on 31 December. Around them sit the usual monthly dates — TDS deposit on 7 December, GSTR-1 on 11 December, GSTR-3B on 20 December. None of these is extendable by habit; the belated-return and FAST-DS windows, in particular, do not reopen. Verified November 2026 · TaxGST.in
November is the month of extensions — the audit ITR deadline moved to 21 November, the ITC claim window runs to 30 November — but December is the month of hard stops. Four different deadlines land in December, three of them on the 31st, and each one belongs to a different law with different consequences for missing it. Here is the month, date by date, with what each one actually costs to miss.
For the full calendar, start with the tax compliance calendar hub — GST, ITR and TDS due dates in one place, and for the month just ending, the November 2026 due-dates calendar covers the 21 November ITR and 30 November ITC deadlines that lead into this month.
December 2026 at a glance
| Date | What is due | Who it hits |
|---|---|---|
| 7 Dec (Mon) | TDS/TCS deposit for November | Every deductor/collector |
| 10 Dec (Thu) | GSTR-7 (TDS) and GSTR-8 (TCS) for November | Government deductors; e-commerce operators |
| 11 Dec (Fri) | GSTR-1 for November | Monthly GST filers |
| 15 Dec (Tue) | Advance tax — third instalment, 75% cumulative | Taxpayers with liability above ₹10,000 after TDS |
| 20 Dec (Sun) | GSTR-3B for November | Monthly GST filers |
| 25 Dec (Fri) | PMT-06 challan for November | QRMP quarterly filers |
| 31 Dec (Thu) | GSTR-9 and GSTR-9C for FY 2025-26 | Businesses above ₹2 crore (9C above ₹5 crore) |
| 31 Dec (Thu) | Belated ITR for AY 2026-27 | Anyone who missed the original deadline |
| 31 Dec (Thu) | FAST-DS foreign-assets disclosure closes | Small taxpayers with undisclosed foreign assets/income |
15 December: advance tax, third instalment
By 15 December you must have paid 75% of your total advance-tax liability for FY 2026-27 — the cumulative figure, including June (15%) and September (45%). The rule applies to anyone whose tax payable after TDS exceeds ₹10,000, except senior citizens without business income, who are exempt from advance tax. The people who get caught are not the salaried — employer TDS usually covers them — but those with FD interest, rent, capital gains or freelance income on top of salary. Shortfall interest under Section 234C runs at 1% per month, and if less than 90% of your liability is paid by 31 March, Section 234B interest applies on top. Fold any bonus, property sale or gains booked this year into the 15 December payment. The advance-tax guide works through the instalment maths with examples.
31 December: GSTR-9 and GSTR-9C for FY 2025-26
The annual GST returns close the FY 2025-26 cycle. GSTR-9 is mandatory above ₹2 crore turnover and optional below it; GSTR-9C, the self-certified reconciliation, applies above ₹5 crore. Filing was enabled on the portal from 8 October 2026 under a GSTN advisory dated 13 October 2026, and the statutory deadline under Section 44 of the CGST Act is 31 December 2026. Here is the catch: the annual return is not the deadline for claiming last year’s input tax credit — that was 30 November 2026 under Section 16(4), and credit unclaimed by then is lost even if GSTR-9 is filed on time. The GSTR-9 and GSTR-9C filing checklist walks through the reconciliation steps before you file.
31 December: belated ITR for AY 2026-27 — the last chance
If you missed the ITR deadlines for AY 2026-27 — 31 July for salaried individuals, 31 August for non-audit business cases, 21 November for audit cases (extended by CBDT Circular No. 07/2026) — the belated-return window under Section 139(4) runs till 31 December 2026. After that date there is no belated return for this assessment year. Filing late carries a late fee under Section 234F of up to ₹5,000, interest under Sections 234A/B/C, and one cost people forget: business losses (other than house-property loss) cannot be carried forward from a belated return. A revised return under Section 139(5) stays open longer — till 31 March 2027 — but only if you filed an original or belated return first; a revised return cannot rescue someone who never filed at all. The belated and revised return guide covers both windows and the ITR-U route that remains after December.
31 December: FAST-DS closes — the foreign-assets window
The Foreign Assets Disclosure Scheme (FAST-DS) window — Form 1, open from 16 August to 31 December 2026 — is the last of the three 31 December deadlines and the least forgiving. For undisclosed foreign assets or income up to ₹1 crore, the scheme charges 30% tax plus an equal amount (60% in total) in exchange for immunity under the Black Money Act; for assets that were taxed but not reported, up to ₹5 crore, the cost is a flat ₹1 lakh fee. Fair market value is taken as on 31 March 2026. This is aimed squarely at small taxpayers — NRIs, returned NRIs, students and tech employees with overseas accounts or ESOPs — and after 31 December the scheme’s terms are gone. The FAST-DS guide explains who qualifies and what to disclose.
The monthly rhythm around the big dates
The rest of December is the ordinary monthly cycle. TDS and TCS deducted in November must be deposited by 7 December; GSTR-7 and GSTR-8 follow on 10 December; GSTR-1 for November is due 11 December and GSTR-3B on 20 December; QRMP filers pay through PMT-06 by 25 December. None of these moved — the 1 November GST process reforms changed registration, refunds and discounts, not filing dates. And one November item is still open as December begins: pensioners must submit their life certificates by 30 November, and the FY 2025-26 ITC claim window closes the same day.
What to do this week
- Advance-tax payers: compute your FY 2026-27 liability to date, subtract TDS and the June and September instalments, and pay the balance to reach 75% by 15 December.
- GST businesses above ₹2 crore: finish the GSTR-9 reconciliation now — do not leave the annual return to the last week, when the portal is at its slowest.
- Anyone who has not filed ITR for AY 2026-27: file the belated return before 31 December; after that date the window is shut.
- Anyone with undisclosed foreign assets: decide on FAST-DS before 31 December — the scheme does not reopen.
- Everyone: check the monthly dates — 7, 11 and 20 December — and set reminders now, not on the day.
FAQs
What is the advance-tax due date in December 2026?
15 December 2026 — the third instalment, taking cumulative payment to 75% of the year’s liability. It applies where tax payable after TDS exceeds ₹10,000.
What is the last date for GSTR-9 for FY 2025-26?
31 December 2026. GSTR-9 is mandatory above ₹2 crore turnover; GSTR-9C applies above ₹5 crore. The ITC claim deadline for FY 2025-26 was earlier — 30 November 2026 under Section 16(4).
Can I file a belated ITR after 31 December 2026?
No. The belated window under Section 139(4) for AY 2026-27 closes on 31 December 2026. After that, only an updated return (ITR-U) remains, with its own conditions and additional tax.
What is FAST-DS and when does it end?
The Foreign Assets Disclosure Scheme for small taxpayers: undisclosed foreign assets/income up to ₹1 crore at 30% tax plus an equal penalty (60% total), or a flat ₹1 lakh fee for taxed-but-unreported assets up to ₹5 crore. The window closes 31 December 2026.
Sources
Section 44, CGST Act, 2017 (GSTR-9 due 31 December 2026); GSTN Advisory dated 13 October 2026 (GSTR-9/9C enabled from 8 October 2026). Section 16(4) (ITC claim deadline 30 November 2026). Sections 234B and 234C — advance-tax instalments (15 June, 15 September, 15 December, 15 March; 75% by the third). Section 139(4) — belated return till 31 December 2026; Section 139(5) — revised return till 31 March 2027; Section 234F — late fee up to ₹5,000. CBDT Circular No. 07/2026, dated 28 September 2026 (audit-category ITR extension to 21 November 2026). FAST-DS: CBDT notification, Form 1 window 16 August – 31 December 2026. Notification No. 03/2026–Central Tax, dated 26 October 2026.
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.