C.K. Gupta
Meera sold her late father’s plot in Jaipur for ₹1.2 crore. Her gain, after indexation, came to ₹48 lakh — and at 12.5%, the tax was ₹6 lakh. Then her CA asked one question: had she put any of it in capital gains bonds? She had not, and the six-month window was already half gone. That is the story of this exemption — it is generous, it is simple, and it expires quietly while you are busy with the sale paperwork.
What Section 85 actually does
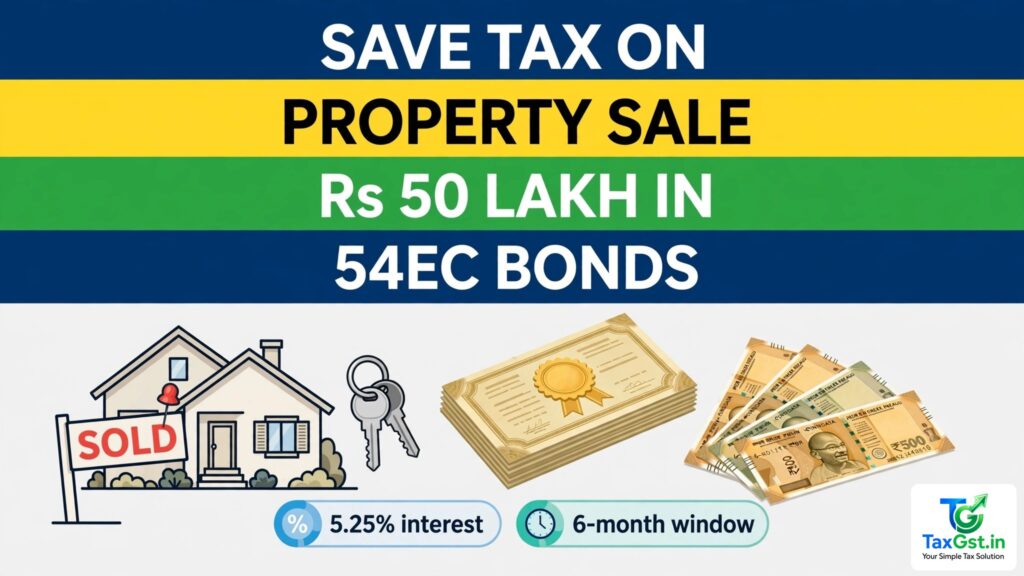
Section 85 of the Income-tax Act, 2025 — the provision everyone still calls Section 54EC, its number under the 1961 Act — says long-term capital gains from selling land or a building are not taxed to the extent you invest them in specified long-term bonds within six months of the transfer. The exemption is capped at ₹50 lakh, counted across the tax year of the sale and the next tax year together. Sell a plot, invest the gain in bonds, pay no tax on the invested part. The underlying conditions did not change when the section was renumbered from 1 April 2026 — only the number did. If you are comparing routes, our guide to the 12.5% vs 20% indexation choice on house sales explains how the gain itself is computed first.
The four rules, with no fine print hidden
| Rule | The detail |
|---|---|
| Only land or building | The gain must be long-term and from land, a building, or both. Gains on shares, mutual funds, gold or jewellery do not qualify. |
| Six-month window | Invest within six months of the date of transfer. Day 181 is too late — there is no extension and no condonation. |
| ₹50 lakh cap | Maximum investment across the year of sale and the following tax year together. Invest ₹50 lakh in year one and nothing more qualifies in year two. |
| Five-year lock-in | Bonds are redeemable after five years. Transfer, convert or pledge them early and the exemption is withdrawn. |
Which bonds, and what they pay
The eligible bonds are five-year bonds issued on or after 1 April 2018 by NHAI or REC Limited, or any other issuer the Central Government notifies. In practice, four issuers have open series for FY 2026-27, all rated AAA and all paying 5.25% a year:
| Issuer | Status in 2026 | Coupon |
|---|---|---|
| REC Limited | Open series, FY 2026-27 | 5.25% p.a. |
| Power Finance Corporation (PFC) | Open series, FY 2026-27 | 5.25% p.a. |
| Indian Railway Finance Corporation (IRFC) | Open series, FY 2026-27 | 5.25% p.a. |
| HUDCO | Notified by CBDT Notification No. 31/2025, dated 7 April 2025 | 5.25% p.a. |
| NHAI | Series closed to new money since 2022; existing holders keep bonds to maturity | — |
Bonds come in ₹10,000 units, with a minimum investment of ₹20,000 (two bonds). The 5.25% interest is paid annually and is fully taxable at your slab rate — the exemption covers the capital gain, never the interest. Before investing, read the issuer’s current information memorandum: series and terms change, and the coupon follows the rate cycle.
Worked examples — what you actually save
Example 1 — gain within the cap. You sell a plot and make a long-term gain of ₹40 lakh. You invest the full ₹40 lakh in REC bonds within six months. Tax on the gain: nil. You save 12.5% × ₹40 lakh = ₹5 lakh (plus 4% cess, ₹5.2 lakh in all). The bonds pay ₹2.1 lakh a year in interest, taxable at your slab.
Example 2 — gain above the cap. Your gain is ₹80 lakh. You invest the maximum ₹50 lakh. The remaining ₹30 lakh is taxed at 12.5% — ₹3.75 lakh, plus cess ₹3.9 lakh. The cap is per person, per sale window: a couple selling a jointly-owned property can each invest up to ₹50 lakh against their own share of the gain, if the ownership and the gain are genuinely split. Before you plan around the numbers, work out your numbers on the income tax calculator.
Example 3 — the timing trap. You sell on 10 May 2026 and plan to invest “in a few months”. The window closes on 10 November 2026. Invest on 11 November and the exemption is zero — the date of transfer, not the date the money reaches your account, starts the clock. Mark the six-month date on the day you sign the sale deed.
The early-exit trap that cancels everything
Here is the catch most sellers miss. If you transfer the bonds, convert them into money, or pledge them as security for a loan before five years are up, the exempted amount is treated as long-term capital gains of the year in which you do it — the tax you saved comes back, with interest. A capital gains bond is not a liquid investment and not collateral. If you may need the money within five years, this is the wrong parking spot; a new house under Section 82 (old Section 54) may fit better, though that route carries its own conditions. A recent court ruling shows how seriously the department treats these exemptions — see the Bombay High Court’s Section 54F second-flat ruling for a sense of how exemption disputes play out.
54 vs 54F vs 54EC — which exemption fits your sale
| Section 82 (old 54) | Section 85 (old 54EC) | Section 86 (old 54F) | |
|---|---|---|---|
| You sold | A residential house | Land or a building | Any long-term asset except a house |
| You buy | Another residential house | Specified 5-year bonds | One residential house |
| Deadline | Buy 1 year before / 2 years after; build within 3 years | Within 6 months | Same windows as Section 82 |
| Cap | New house cost counted up to ₹10 crore | ₹50 lakh | New house cost counted up to ₹10 crore |
For the full picture of which return to file and how the gain is reported, see the income tax hub guides and our plain-English guide to what an ITR is.
FAQs
Does Section 85 cover gains on shares or mutual funds?
No. Only long-term gains from land or a building qualify. Share and mutual-fund gains have their own regime and cannot be parked in these bonds.
Can I invest ₹50 lakh this year and ₹50 lakh next year from the same sale?
No. The ₹50 lakh cap covers the tax year of the transfer and the following tax year together. Split the investment across two years if the sale is late in the year, but the total stays ₹50 lakh.
Is the 5.25% interest tax-free?
No. The interest is taxable at your slab rate every year. Only the capital gain you invested is exempt.
What if I sell the property before 23 July 2024 rules apply?
For sales on or after 23 July 2024, property gains are taxed at a flat 12.5% without indexation. Older sales could choose 20% with indexation. The Section 85 exemption works the same way under either rate — it shelters the gain, whatever the rate.
Can NRIs use Section 85 bonds?
Yes — the section applies to any assessee, resident or non-resident, with a long-term gain on Indian land or a building. The TDS on the sale itself is a separate matter; the exemption is claimed in the return.
Sources
Income-tax Act, 2025 — Section 85 (“Capital gains not to be charged on investment in certain bonds”, successor to Section 54EC of the Income-tax Act, 1961); CBDT Notification No. 31/2025, dated 7 April 2025 (HUDCO bonds notified as long-term specified assets); Finance Act, 2024 (12.5% long-term capital gains rate on property from 23 July 2024); issuer information memoranda of REC, PFC, IRFC and HUDCO for FY 2026-27 series (5.25% coupon, five-year tenure, ₹10,000 units).
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.