C.K. Gupta
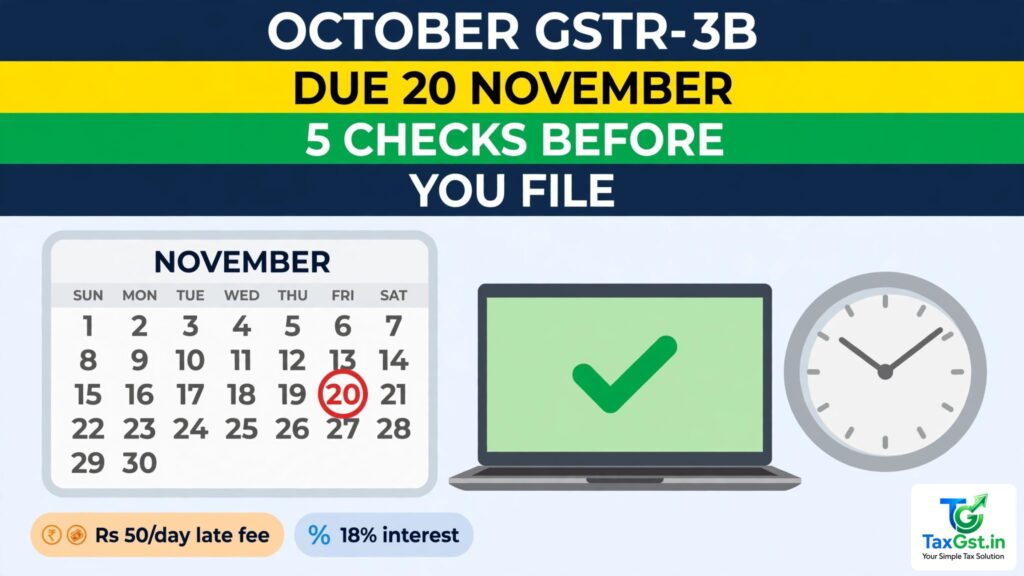
It is the 17th, and your October return is not filed yet. That is fine — you still have three days. What is not fine is treating the 20th as a soft date. GSTR-3B has no grace period: file on the 21st and the portal charges late fee from the first day, and interest starts ticking on the tax you pay in cash. Here are the five checks that keep an ordinary October filing from turning into a penalty notice.
The dates that matter this month
October’s GSTR-1 was due on 11 November — your suppliers’ invoices for the month are already on the portal. Your GSTR-3B, the return where you actually pay, is due on Friday, 20 November 2026 for monthly filers. If you are on the quarterly QRMP scheme, you do not file a 3B on the 20th at all — your October–December return is due on 22 January 2027, but you still owe a monthly tax payment for October by 25 November. For the full month-by-month picture, keep the compliance calendar hub bookmarked — it carries every GST and income-tax date in one place.
| What | Due date | Who it covers |
|---|---|---|
| GSTR-1, October 2026 | 11 November 2026 | Monthly filers (already passed) |
| GSTR-3B, October 2026 | 20 November 2026 | Monthly filers |
| PMT-06 payment, October 2026 | 25 November 2026 | QRMP quarterly filers |
| ITC cut-off, FY 2025-26 | 30 November 2026 | Everyone — last chance for last year’s credit |
| GSTR-3B, Oct–Dec 2026 quarter | 22 January 2027 | QRMP quarterly filers |
Check 1 — Reconcile GSTR-2B before you touch the payment
Open your auto-generated GSTR-2B for October and compare it with your purchase register, invoice by invoice. Here is the catch: there is no provisional ITC any more. The old 5% cushion under Rule 36(4) was withdrawn from 1 January 2022, so credit that is not in your 2B is credit you cannot claim this month — however genuine the purchase. If a supplier filed late or missed your invoice, chase them now; the credit lands in a later month’s 2B, and you claim it then. Claiming ITC your 2B does not show is the single most common reason for a mismatch notice, and the department’s system flags it automatically. Our guide to ITC missing from GSTR-2B walks through the seven real reasons and the fix for each.
Check 2 — The 30 November ITC cut-off is ten days behind this return
October’s 3B is the last monthly return before the Section 16(4) deadline. Any input tax credit relating to FY 2025-26 — invoices, debit notes, import bills of entry — must be claimed by 30 November 2026, or by the date you file your annual return, whichever is earlier. Miss it and the credit is gone for good; there is no condonation route. If your books still hold unclaimed 2025-26 invoices, this is the week to pull them into October’s return. The full deadline mechanics, including the QRMP quarter and the Rule 37A reversal, are in our 30 November ITC deadline guide.
Check 3 — Know exactly what a late filing costs
Delay is not free, but it is at least predictable. Work it out before you decide to “file next week”:
| Cost | Rate | How it applies |
|---|---|---|
| Late fee (Section 47) | ₹50 a day | ₹25 CGST + ₹25 SGST, capped at ₹5,000 per return |
| Late fee, nil return | ₹20 a day | Capped at ₹500; small taxpayers get lower caps under CBIC notifications |
| Interest (Section 50) | 18% a year | On the tax paid in cash only, from 21 November until payment |
A worked example makes it concrete. Say your October liability is ₹1,00,000, you have ₹70,000 of ITC, and you file five days late. The cash tax is ₹30,000. Late fee: 5 × ₹50 = ₹250. Interest: ₹30,000 × 18% × 5/365 = ₹74. Total damage: ₹324 — small, but it is money paid for nothing, and the late fee keeps growing at ₹50 a day until you file. Our GSTR-3B late fee and interest guide has the same maths for longer delays, where the numbers stop being trivial.
Check 4 — Pay in the right order, then file
GSTR-3B cannot be filed until the electronic ledgers hold enough balance. Use ITC first — IGST credit against IGST, then CGST and SGST; CGST and SGST credits stay within their own heads — and pay the balance in cash through a PMT-06 challan. Pay first, file second: the portal will not let you submit with a shortfall, and a challan generated on the 20th but paid on the 21st is a late payment. If cash is tight, remember interest runs only on the cash portion — every rupee of ITC you use is a rupee that earns no interest. Not sure what you owe? Work out your GST numbers on the GST calculator before you open the portal.
Check 5 — QRMP filers: you have a different deadline
If your turnover is up to ₹5 crore and you opted for the quarterly QRMP scheme, do not file a GSTR-3B on 20 November — there is nothing to file. Your October–December quarter return is due on 22 January 2027. What you do owe is the monthly tax payment for October, due by 25 November through PMT-06: either 35% of the previous quarter’s cash-paid tax, or a self-assessed amount on your actual October liability. Paying nothing in October and settling the whole quarter in January is not an option — interest applies to the shortfall. For the full scheme rules, see the GST hub guides.
If you already filed October wrong
GSTR-3B has no revision. A wrong figure — a missed invoice, an excess ITC claim, a typo in the liability table — is corrected in the next month’s return, not by re-filing October. Outward-supply mistakes go through an amended GSTR-1 in the following month; ITC mistakes are adjusted in November’s 3B. File October on time even if it is imperfect; a late return with a correction costs far less than a late return with nothing filed.
FAQs
What happens if I file on 21 November instead of the 20th?
One day late is still late: ₹50 late fee (₹20 for a nil return) plus interest at 18% a year on the cash tax, counted from 21 November. File on the 20th even if you must correct something in November’s return.
Can I file GSTR-3B without paying the tax first?
No. The portal blocks filing until the credit and cash ledgers cover the full liability in Table 3.1. Generate and pay the PMT-06 challan first, then submit.
I am a QRMP filer. Is 20 November my deadline?
No. Your quarterly GSTR-3B is due 22 January 2027. Your October obligation is the PMT-06 monthly payment by 25 November 2026.
Can I revise October’s GSTR-3B after filing?
No — GSTR-3B cannot be revised. Correct outward-supply errors in next month’s GSTR-1 and ITC errors in November’s GSTR-3B.
Does the 30 November ITC deadline apply to October invoices too?
No. The 30 November 2026 cut-off under Section 16(4) applies only to credit relating to FY 2025-26. October 2026 invoices belong to FY 2026-27 and can be claimed until 30 November 2027.
Sources
CGST Act, 2017 — Section 39 (furnishing of returns, GSTR-3B due on the 20th of the succeeding month), Section 47 (late fee), Section 50 (interest on delayed payment of tax), Section 16(4) (time limit for taking ITC); CGST Rules, 2017 — Rule 61 (form and manner of GSTR-3B); GSTN due-date calendar for November 2026. Late-fee caps as notified by CBIC under Section 47.
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.