C.K. Gupta
In short
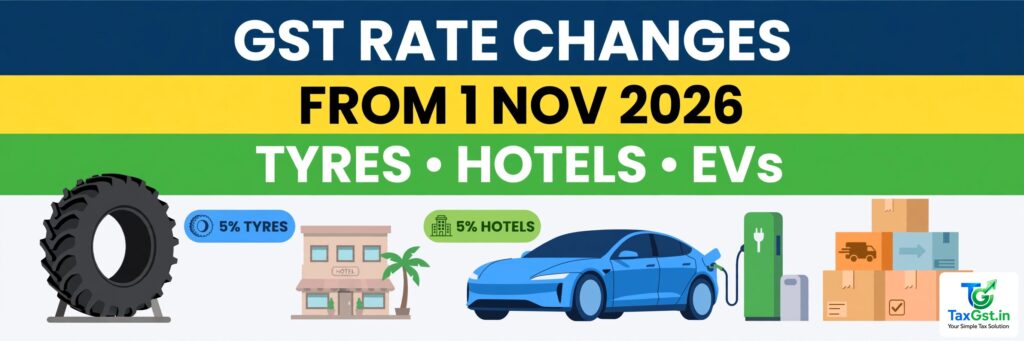
From 1 November 2026, GST rates changed on a short list: retreaded tractor tyres 18% to 5%, psyllium (isabgol) seeds fully exempt, hotels, restaurants and caterers at 5% can now claim input tax credit on same-line input services, electric-vehicle transport and rentals got 5%/18% entries, and delivery through e-commerce operators moved to 5% without credit. The changes come from CBIC Notifications 2/2026 to 10/2026-Central Tax (Rate), dated 27 October 2026, implementing the 57th GST Council’s recommendations. If you invoiced across 1 November, Section 14 of the CGST Act — not the invoice date alone — decides the rate. Verified November 2026 · TaxGST.in
A tyre retreader in Ludhiana invoiced a set of retreaded tractor tyres on 30 October at 18%. The same tyres invoiced on 3 November attract 5%. Nothing about the tyres changed — the notification did. For the wider picture, keep the GST hub — rates, registration and returns in one place open alongside this guide.
Where the changes come from
The 57th GST Council met on 8 October 2026 and recommended a package of rate, exemption and procedure changes. A Council recommendation changes nothing by itself — it becomes law only when notifications issue. CBIC issued the rate notifications, numbered 2/2026 to 10/2026-Central Tax (Rate), on 27 October 2026 (the CBIC portal lists 28 October), and most took effect on 1 November 2026. The scrap and e-waste changes in that package already have their own guide — the new reverse-charge and 2% GST TDS rules for scrap, used cooking oil and e-waste — so this article sticks to the rate and exemption items. The Council’s decisions in full are covered in our explainer on the 57th GST Council meeting.
The rate changes, item by item
Two goods and four service entries changed rate or condition. Here is the full list, with the notification entry for each so you can check it yourself.
| Item | Up to 31 Oct 2026 | From 1 Nov 2026 | Notification |
|---|---|---|---|
| Retreaded tractor tyres (HSN 4012) | 18% | 5% | 2/2026-CT(R), Sch. I, S. No. 272A |
| Psyllium (isabgol) seeds (1211 90 13) | 5% if frozen or dried; nil if fresh or chilled | Nil — fully exempt | 3/2026-CT(R), S. No. 87A |
| Delivery services (not postal or courier) through an e-commerce operator | 18% (local delivery only) | 5% without input tax credit | 6/2026-CT(R), entry 12(iii) |
| Transport of passengers by electric vehicle, battery charging included in the fare | No separate entry | 5% with same-line credit, or 18% | 6/2026-CT(R), entry 8(vib) |
| Renting of an electric vehicle with charging included | No separate entry | 5% with same-line credit, or 18% | 6/2026-CT(R), entries 10(ib) and 10(ic) |
| Hotel rooms up to ₹7,500 a day; restaurants; railway catering; outdoor catering | 5% without credit | 5% with same-line credit | 6/2026-CT(R), entries 7(i) to 7(v) |
“Same-line credit” is the phrase to get right: at the 5% rate, you may claim credit only on services bought from another supplier of the same service — a hotel can claim credit on a room bought from another hotel, not on laundry or housekeeping. There is also a cap: for hotels, outdoor catering and electric vehicles, if the other supplier charged central tax above 2.5%, your credit stops at 2.5% — a hotel buying a ₹10,000 room from another hotel charging 9% CGST (₹900) may take only ₹250. Restaurants and railway catering have no such cap. The fertiliser entry (HSN 3101) stays at 5%, with a new Explanation covering sea-weed extract based bio-stimulants.
New exemptions from 1 November
Notification 7/2026-CT(R) adds six exemptions to the services list:
- Storage or warehousing of seeds meant for sowing (cereals, pulses, fruits and vegetables were already exempt) (entry 24B).
- Curing of coffee supplied to coffee cultivators (entry 54A).
- Services of the Seamen’s Provident Fund Organisation to its members (entry 31AA).
- Grant of toll rights (right of way or licence to collect toll) by the Central or a State Government, a local authority or a government entity (entry 42A).
- Helicopter travel on a seat-share basis to or from the North-Eastern States, Sikkim or Bagdogra, helipads included (clause 15(aa)).
- Import of services by the Indian establishment of a foreign shipping company from a related person or its other establishments abroad, without consideration — IGST only (entry 10M).
Two procedure items travel with the package. Notification 10/2026-CT(R), under Section 148, sets a special procedure for Toll-Operate-Transfer concessionaires: tax on operation and maintenance services is paid as amounts are debited from the escrow account. Notification 3/2026-CT brings Sections 153 to 155 of the Finance Act, 2026 into force from 1 November — backing for the new post-supply discount rules (Sections 15(3)(b) and 34(1)) and refund changes (Sections 54(6) and 54(14)), including the 90% provisional refund for inverted-duty claims — see our guide to the new Rule 89(5) refund formula.
The straddle problem: supplies across 1 November
Here is the catch: a rate change does not apply by invoice date alone. Section 14 of the CGST Act decides the rate when supply, invoice and payment fall on different sides of the change — the two events on the same side of 1 November decide the rate. The notification’s own worked examples for retreaded tractor tyres:
| Supply | Invoice | Payment | Rate | Why |
|---|---|---|---|---|
| 28 Oct | 28 Oct | 5 Nov | 18% | Supply before; invoice before, payment after — date of invoice, Sec 14(a)(ii) |
| 30 Oct | 3 Nov | 4 Nov | 5% | Supply before; invoice and payment after — the earlier of the two, Sec 14(a)(i) |
| 4 Nov | 30 Oct | 31 Oct | 18% | Supply after; invoice and payment before — the earlier of the two, Sec 14(b)(ii) |
| 4 Nov | 30 Oct | 6 Nov | 5% | Supply after; invoice before, payment after — date of payment, Sec 14(b)(i) |
The same test applies to every change in this list, including the new exemptions, where the “new rate” is nil. Check the three dates on any October invoice paid in November.
What to do before your next return
- Update item masters now: retreaded tractor tyres (4012) at 5%, psyllium seeds (1211 90 13) at nil — an old 18% master is the most common way this change becomes a wrong return.
- Hotels, restaurants and caterers at 5%: review which same-line input services now qualify for credit from 1 November — and apply the 2.5% cap where it binds.
- E-commerce sellers and delivery partners: delivery through an operator is now 5% without credit, and under Notification 9/2026-CT(R) the operator pays the tax on delivery services other than postal and courier supplied through it (earlier, local delivery only) — unless the delivery supplier is itself liable to register under Section 22(1). Cab hire with fuel to a body corporate stays under reverse charge unless the supplier charges CGST at 9% (up from 6%).
- Scrap and e-waste buyers and sellers: the reverse-charge, registration and 2% TDS rules from the same package are covered in the scrap RCM and TDS guide — including the self-invoice and payment-voucher discipline.
- Do not treat the April 2027 items as live: the Council also recommended deeper law and return reforms that need statutory amendments and apply from 1 April 2027.
FAQs
From which date do the new GST rates apply?
1 November 2026, under CBIC Notifications 2/2026 to 10/2026-Central Tax (Rate) dated 27 October 2026. For supplies straddling the date, Section 14 of the CGST Act decides the rate from the supply, invoice and payment dates — not the invoice date alone.
What is the GST rate on retreaded tractor tyres now?
5% from 1 November 2026, down from 18%, under Notification 2/2026-CT(R) (new Schedule I, S. No. 272A). A tyre supplied and invoiced in October but paid in November still attracts 18% under Section 14(a)(ii).
Can hotels and restaurants claim input tax credit at 5% now?
Yes — from 1 November 2026, hotels (rooms up to ₹7,500 a day), restaurants, railway catering and outdoor catering charging 5% may claim credit on same-line input services. For hotels, outdoor catering and electric vehicles the credit is capped at 2.5% where the other supplier charged more. Restaurants and railway catering have no cap.
Sources
CBIC Notifications No. 2/2026 to 10/2026-Central Tax (Rate), dated 27 October 2026 (effective 1 November 2026); CBIC Notifications No. 3/2026, 4/2026, 6/2026 and 7/2026-Central Tax, dated 26–27 October 2026; 57th GST Council press release, 8 October 2026; Finance Act, 2026 (No. 4 of 2026), Sections 153 to 155; Section 14 and Section 148 of the Central Goods and Services Tax Act, 2017.
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.