C.K. Gupta
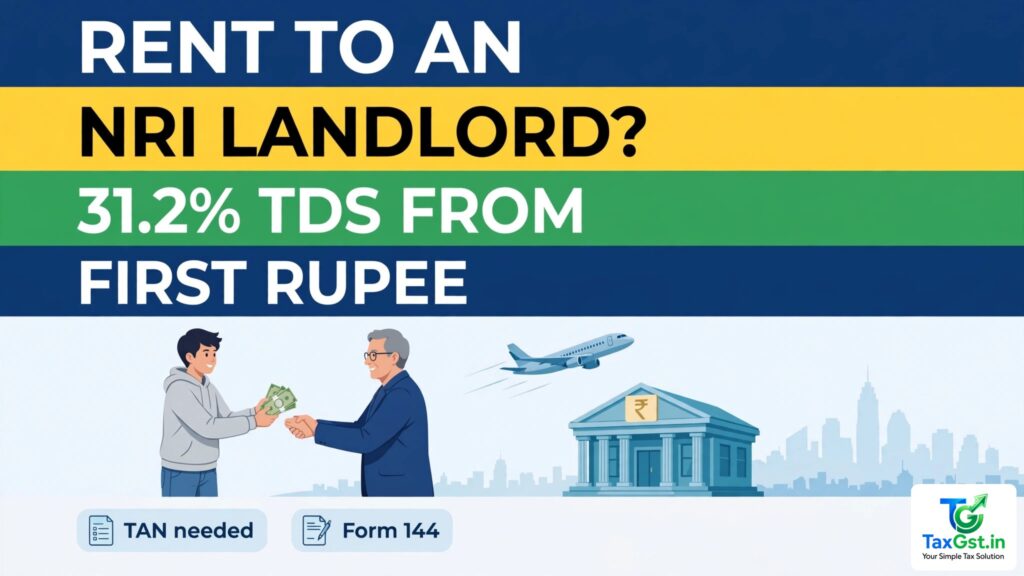
Amit rents a 2BHK in Gurugram for ₹40,000 a month. His landlord moved to Dubai last year. Amit did what most tenants do: he deducted 2% TDS, the rate for resident landlords, and paid the rest. He was wrong by ₹11,680 a month. The moment a landlord becomes a non-resident, the rent stops being covered by the resident-landlord provisions and moves under the non-resident TDS regime — a different section, a different rate, and a much heavier compliance load that sits entirely on the tenant.
The section that applies — and the one that does not
Rent to a resident landlord is covered by Section 393(1) of the Income-tax Act, 2025 — 2% above ₹50,000 a month, no TAN needed, simple challan-cum-statement. None of that applies when the landlord is a non-resident. The payment falls under Section 393(2), Table Sl. No. 17 (old Section 195): any person paying a sum chargeable to tax to a non-resident must deduct tax at the rates in force, at the time of payment or credit, whichever is earlier. For rent, the rate in force is the maximum marginal rate — 30% — plus surcharge where applicable and 4% health and education cess. The full comparison with the resident rules is in our rent TDS guide under Section 393.
| Resident landlord | NRI landlord | |
|---|---|---|
| Section | Section 393(1) (old 194-IB) | Section 393(2) (old 195) |
| TDS rate | 2% above ₹50,000/month | 30% + cess = 31.2%, from the first rupee |
| Threshold | ₹50,000 a month | None — even ₹8,000 a month attracts TDS |
| TAN required | No — tenant uses PAN | Yes — apply in Form 49B |
| Deposit deadline | 30 days from month-end | 7th of the following month |
| Quarterly return | Form 141 (old 26QC) | Form 144 (old 27Q) |
| TDS certificate | Form 131 (old 16C) | Form 131 (old 16A) |
Worked example — what Amit should have deducted
Rent ₹40,000 a month. At 31.2%, the TDS is ₹12,480 a month and the landlord receives ₹27,520. Amit deducted 2% — ₹800 — so he under-deducted ₹11,680 every month. Over a year, that is ₹1,40,160 of tax he should have deducted and did not. The shortfall is his liability, not the landlord’s: interest at 1% a month for late deduction and 1.5% a month for late deposit, plus a penalty that can run up to the amount of TDS itself. The landlord, meanwhile, is taxed on only 70% of the net annual value after the 30% standard deduction — so the 31.2% TDS is usually far more than his final tax, and the excess comes back as a refund when he files his return. For the mirror-image problem — buying a property from an NRI seller — see our TDS guide for property purchases from NRI sellers.
The tenant’s compliance checklist
- Get a TAN before the first deduction. A PAN alone is not enough for non-resident TDS. Apply in Form 49B through the Protean/NSDL portal. This is the step that stops most tenants — an individual tenant with no business has usually never needed a TAN.
- Deduct before paying. Deduct 31.2% (or the lower-certificate rate, if the landlord has one) from the gross rent, at the time of payment or credit, whichever is earlier. The rent must flow to the landlord’s NRO account — never to an NRE account.
- Deposit by the 7th of the next month. Pay through challan ITNS-281 under your TAN. Tax deducted in March is due by 30 April.
- File Form 144 every quarter. The non-resident TDS return (successor to Form 27Q) is due 31 July, 31 October, 31 January and 31 May. It captures the landlord’s PAN — and where no PAN is available, the landlord’s foreign address, contact and tax identification number.
- Issue the certificate. Generate Form 131 (successor to Form 16A) from TRACES and give it to the landlord within 15 days of the return’s due date. Without it, the landlord cannot claim credit for the TDS when filing.
- File Form 15CA before each credit. Every payment to a non-resident needs a Form 15CA declaration; once the annual rent crosses ₹5 lakh, a CA-certified Form 15CB is needed too. Check the credit in Form 168 (successor to Form 26AS) and the AIS before the landlord files.
All the rates, thresholds and forms for every TDS situation live on the TDS hub.
How the landlord can pay less than 31.2%
Two routes. First, the landlord can apply for a lower-deduction certificate under Section 395(1) (old Section 197) — Form 128 under the Income-tax Rules, 2026 (earlier Form 13) — showing that his actual Indian tax liability is lower than 31.2%. With rental income as his only Indian income, the effective rate is often 10–15%. Our lower TDS certificate guide explains the application. Second, a tax treaty can cut the rate — but for rent, most Indian treaties do not offer a lower rate than the domestic law, so the certificate is usually the better route. Note also that a landlord with no PAN faces the higher 20% no-PAN rate provisions under Section 397 — get the landlord’s PAN on the rent agreement from day one. Buying rather than renting from an NRI? The property-purchase route uses a different form — see our Form 141 guide for property purchases.
FAQs
My landlord became an NRI mid-tenancy. When does Section 195 start applying?
From the day his residential status changes — the status is tested for the tax year, and once he is non-resident, every payment after that point falls under Section 393(2). Confirm the status in writing before you change the deduction; a landlord who merely lives abroad but remains resident is still covered by the resident rules.
Can I deduct 2% and let the landlord pay the balance in his return?
No. The obligation to deduct at the correct rate sits on you, the payer. Under-deduction is your default, with interest and penalty, even if the landlord later pays the full tax.
What if the rent is only ₹15,000 a month?
TDS still applies. Section 195 has no threshold: 31.2% of ₹15,000 is ₹4,680 a month, and the full TAN–deposit–return cycle applies exactly as it does for ₹1 lakh rent.
Does the landlord get the excess TDS back?
Yes. The NRI landlord files an Indian return, claims the 30% standard deduction on the net annual value, is taxed at slab rates, and the excess TDS over the final liability comes back as a refund. The Form 131 certificate and Form 168 credit are the proof.
Do I need Form 15CA if I pay into the landlord’s Indian NRO account?
Form 15CA is required before remitting money abroad. A payment into an Indian NRO account is not a remittance abroad, so no 15CA is needed for that leg — but if the landlord later repatriates the rent, the bank will ask for 15CA/15CB at that stage.
Sources
Income-tax Act, 2025 — Section 393(2), Table Sl. No. 17 (TDS on payments to non-residents, successor to Section 195 of the Income-tax Act, 1961); Section 395(1) (lower deduction certificate, successor to Section 197); Section 397 (higher rate where PAN is not furnished, successor to Section 206AA); Income-tax Rules, 2026 — Rule 220 and Forms 128, 131 and 144 (CBDT Notification No. 22/2026); Finance Act rates in force for tax year 2026-27 (30% maximum marginal rate for individuals, 4% health and education cess, surcharge 10%–37% above ₹50 lakh).
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.