C.K. Gupta
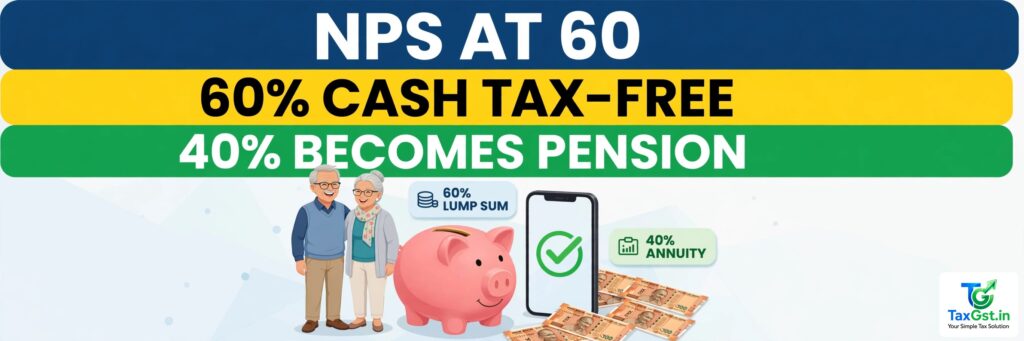
At 60, an NPS subscriber can take up to 60% of the corpus as a tax-free lump sum and must use at least 40% to buy an annuity that pays a monthly pension (taxable as income). If the total corpus is ₹5 lakh or less, the whole amount can be withdrawn as a lump sum with no annuity obligation. The lump sum and the annuity purchase itself are tax-free; the pension you receive afterwards is taxed at your slab rate. You can also defer exit or continue contributing until 75. Verified October 2026 · TaxGST.in
Consider a 60-year-old retiring with an NPS corpus of ₹40 lakh — twenty-five years of contributions plus market growth. The question she asks her adviser is simple: “How much of this is actually mine to spend?” The answer surprises most people: ₹24 lakh in hand, tax-free — and ₹16 lakh she will never see as a lump sum, because it must buy a pension. That split, 60/40, is the single most important number in NPS exit planning, and misunderstanding it is how retirees end up short of the cash they were counting on for a house repair, a child’s wedding, or a medical buffer.
For the wider retirement-tax picture, see our deductions hub and our mid-year tax checklist, which covers the NPS ₹50,000 additional deduction while you are still contributing.
The 60/40 rule, with real numbers
On superannuation at 60, the Pension Fund Regulatory and Development Authority (PFRDA) exit rules work like this:
| Corpus at 60 | Lump sum (tax-free) | Must buy annuity | Indicative monthly pension* |
|---|---|---|---|
| ₹10 lakh | ₹6 lakh | ₹4 lakh | ~₹2,000–2,400 |
| ₹25 lakh | ₹15 lakh | ₹10 lakh | ~₹5,000–6,000 |
| ₹40 lakh | ₹24 lakh | ₹16 lakh | ~₹8,000–9,600 |
| ₹1 crore | ₹60 lakh | ₹40 lakh | ~₹20,000–24,000 |
*At annuity rates of roughly 5–6% a year from PFRDA-authorised annuity service providers. The pension is taxable in your hands at your slab rate — so a retiree in the 20% slab keeps about 80% of the figure above.
Three tax points are routinely confused. First, the 60% lump sum is fully exempt from tax. Second, the 40% used to buy the annuity is also exempt at purchase — no tax is charged on money moving into the annuity. Third, only the pension that comes out afterwards is taxable, year by year, as pension income. In short: the corpus itself is tax-free on exit; the income stream it produces is not.
The small-corpus exception: ₹5 lakh or less
Here’s the relief valve. If your total accumulated pension wealth is ₹5 lakh or less at exit, you can withdraw the entire amount as a lump sum, with no obligation to buy an annuity at all. For small savers — someone who joined late, or contributed modestly — this avoids the absurdity of a ₹1,500-a-month pension locked away for life. If your corpus is just above the line, the 60/40 rule applies to the whole amount; there is no taper.
A related flexibility: the lump sum need not be taken all at once. You can take it in phased withdrawals — up to 10 years in the current framework — which lets you spread the cash across retirement years rather than holding a large idle balance. And if you do not need the money at 60, you can defer exit, or continue contributing, until 75 — keeping the corpus invested and tax-deferred while your other income is higher.
What you give up when you buy the annuity
Buying an annuity is irreversible. Once ₹16 lakh (in our ₹40 lakh example) goes into the annuity, you cannot exit, switch provider, or reclaim the principal — you own an income stream, not a pot. That is the trade the 60/40 rule forces, and it deserves a clear-eyed comparison before you sign:
- Choose the annuity option carefully. Annuity service providers offer variants — pension for life only, pension with return of purchase price to the nominee, joint-life pension for a spouse. The return-of-purchase-price option pays a lower monthly pension but returns the capital to your family; for many couples, that trade is worth it.
- Compare the pension with your real costs. A ₹8,000 monthly pension sounds solid until it meets rent, medicines and inflation — annuity pensions are generally fixed, not inflation-linked. The 60% lump sum is your inflation hedge; do not spend it all in year one.
- Coordinate with other income. If you also draw EPF pension, rental income or interest, the annuity pension stacks on top for tax purposes and can push you into a higher slab. Timing your exit — and any deferral — around your other income years can save real tax.
- Nominee and spouse first. If your spouse has no independent pension, a joint-life annuity option protects them after you. This is a one-time choice; it cannot be fixed later.
Exit before 60 is a different, harsher deal
Do not confuse the age-60 rules with premature exit. Exit before 60 (other than on death) allows only 20% as a lump sum, with 80% locked into an annuity — and the small-corpus full-withdrawal threshold is ₹2.5 lakh, not ₹5 lakh. If you are considering an early exit, that 80% lock-in is usually the deciding argument against it. Where possible, staying in until 60 — or using partial withdrawal rules for specific needs (illness, children’s education, house purchase, subject to conditions) — leaves far more cash in your hands.
Your exit checklist
- ☐ Check your corpus on the CRA portal and confirm whether you are above or below the ₹5 lakh line.
- ☐ Decide: lump sum now, phased withdrawal, or deferral until 75 — based on other income, not on habit.
- ☐ Get annuity quotes from more than one PFRDA-authorised provider, including the return-of-purchase-price variant.
- ☐ Confirm your nominee and bank details are updated before initiating exit — errors here delay everything.
- ☐ Budget the pension as taxable income at your slab rate, not as the headline figure.
- ☐ Keep the exit statement and annuity policy — the pension will appear in your AIS every year from now on.
For many readers, the practical takeaway is simple: NPS at 60 is not a ₹40 lakh cheque. It is a ₹24 lakh cheque plus a pension — and planning around both halves, rather than assuming the whole pot is spendable, is what keeps retirement comfortable.
FAQs
How much of my NPS corpus can I withdraw at 60?
Up to 60% as a tax-free lump sum; at least 40% must buy an annuity. If the corpus is ₹5 lakh or less, 100% can be withdrawn.
Is the NPS lump sum taxable?
No — the lump sum up to 60% is exempt, and the annuity purchase itself is exempt. The monthly pension received afterwards is taxable at slab rates.
Can I delay my NPS exit beyond 60?
Yes — you can defer exit or continue contributing until age 75, keeping the corpus invested and tax-deferred.
What happens if I exit NPS before 60?
Only 20% can be taken as a lump sum and 80% must buy an annuity; the full-withdrawal threshold is ₹2.5 lakh instead of ₹5 lakh.
Can I change my annuity provider later?
No — annuity purchase is irreversible. Compare providers and options carefully before you buy.
Planning your own exit? Work through the numbers on the NPS calculator — corpus, annuity and monthly pension estimates and compare the withdrawal options in our complete guide to the NPS exit and withdrawal rules.
Sources
Pension Fund Regulatory and Development Authority (PFRDA) NPS exit and withdrawal regulations — superannuation exit at 60 (60% lump sum / 40% annuity), full withdrawal where corpus is ₹5 lakh or less, premature-exit 20/80 rule with ₹2.5 lakh threshold, deferral/continuation until 75. Tax treatment: lump-sum exemption and taxation of annuity pension as income, consistent with the Income-tax Act, 2025 framework for NPS (deductions under the erstwhile Sections 80CCD(1)/(1B) scheme, carried into the new Act). Annuity rate range of 5–6% per year reflects prevailing PFRDA-authorised annuity service provider rates reported in 2026 coverage.
Discover more from TaxGst.in
Subscribe to get the latest posts sent to your email.